Carbon Insetting vs Offsetting: True Cost for Textile Brands
Pull up your brand's decarbonisation budget for the next financial year. Now ask yourself: how much of that line item is going toward buying carbon credits from a registry, and how much is going toward changing what actually happens in your supply chain? For most textile and fashion brands, the honest answer reveals a structural problem — not a climate strategy.
The carbon insetting vs offsetting cost comparison for brands is not simply a question of price per tonne. It is a question of what your climate budget is actually buying, who benefits from it, and whether it will hold up under the scrutiny of regulators, investors, and the Science Based Targets initiative (SBTi) in 2026 and beyond. This post breaks down the true cost structures of both approaches using textile industry benchmarks, so you can make a defensible, financially sound decision about where your budget goes further.
The Budget Question Every Sustainability Director Faces
Sustainability directors at textile and fashion brands are navigating a genuinely difficult trade-off. Carbon offsets are fast to procure, easy to account for, and come with a clear price tag. Carbon insetting — embedding climate action directly into your agricultural or manufacturing supply chain — requires more upfront coordination, longer timelines, and a willingness to engage with farmers, MRV systems, and traceability infrastructure.
The temptation to default to offsets is understandable. But the regulatory and reputational landscape has shifted sharply. The EU's Corporate Sustainability Reporting Directive (CSRD), the SBTi's Corporate Net-Zero Standard, and the growing body of anti-greenwashing legislation in the UK, EU, and India are all moving in the same direction: offsets alone will not satisfy net zero claims, and brands that rely on them heavily are accumulating reputational and compliance risk.
This comparison uses a consistent framework across both approaches: upfront implementation costs, ongoing verification costs, co-benefit value, and long-term scalability. The goal is not to declare a winner in every scenario, it is to give your finance and sustainability teams the data they need to allocate budget intelligently.
Key framing: For textile brands, Scope 3 emissions from raw material production typically represent 60, 80% of total carbon footprint. Any strategy that does not address the supply chain is addressing the wrong problem.
What Carbon Offsetting Actually Costs Textile Brands
The headline price of a carbon offset, often quoted between $5 and $50 per tonne of CO2e on the voluntary carbon market, is only the beginning of the true cost calculation. Understanding the full cost stack is essential before committing budget.
Credit Purchase Prices in 2026
Voluntary carbon market prices have been volatile. Nature-based offsets (forestry, soil carbon, blue carbon) typically trade between $8 and $30 per tonne CO2e, depending on co-benefit ratings and vintage. High-quality credits with additional biodiversity or community development attributes can reach $40–$50 per tonne. Technology-based removal credits (direct air capture, enhanced weathering) command $200–$600 per tonne but are rarely used by fashion brands at scale due to cost. For a mid-size apparel brand needing to offset 50,000 tonnes of CO2e annually, credit procurement alone could run $400,000 to $1.5 million per year at current market rates.
Verification and Registry Fees
Credits listed on registries like Verra (VCS) or Gold Standard carry third-party verification costs that are ultimately passed on to buyers through credit pricing. Brands that develop their own offset projects, rare but not unheard of, face direct verification costs of $15,000 to $80,000 per project cycle, plus annual monitoring fees. Even brands simply purchasing credits must budget for internal due diligence: legal review of credit quality, additionality assessments, and registry account management.
Internal Staff and Procurement Costs
Sourcing high-quality offsets is not a passive activity. Brands need staff time to evaluate project quality, negotiate with brokers, manage registry accounts, and respond to investor or NGO scrutiny of their offset portfolio. A conservative estimate for a mid-size brand is 0.5 to 1.0 FTE equivalent of sustainability staff time annually, plus potential consultant fees for portfolio audits.
The Hidden Costs: Reputational and Regulatory Risk
This is where the offset cost calculation becomes uncomfortable. The SBTi's Corporate Net-Zero Standard explicitly limits the use of offsets for neutralisation claims to residual emissions only, those that cannot be abated. Brands using offsets to compensate for supply chain emissions they have not yet reduced are increasingly exposed to greenwashing allegations. The reputational cost of a single credible greenwashing investigation, in legal fees, brand damage, and lost retail partnerships, can dwarf years of offset expenditure. This risk is not hypothetical; several major fashion brands have faced exactly this scrutiny in 2024 and 2025.
For a deeper look at how to protect your brand from these risks, see our guide on Fashion Brand Net Zero Roadmap: 5 Steps to Verified Climate Targets.
What Carbon Insetting Actually Costs Textile Brands
Carbon insetting places climate investment inside your supply chain, typically at the agricultural origin of your raw materials. For textile brands sourcing cotton from India or Bangladesh, this means funding regenerative farming practices, biochar application, or water management interventions that sequester carbon and generate verified credits attributed to your supply chain.
Program Setup and Farmer Onboarding
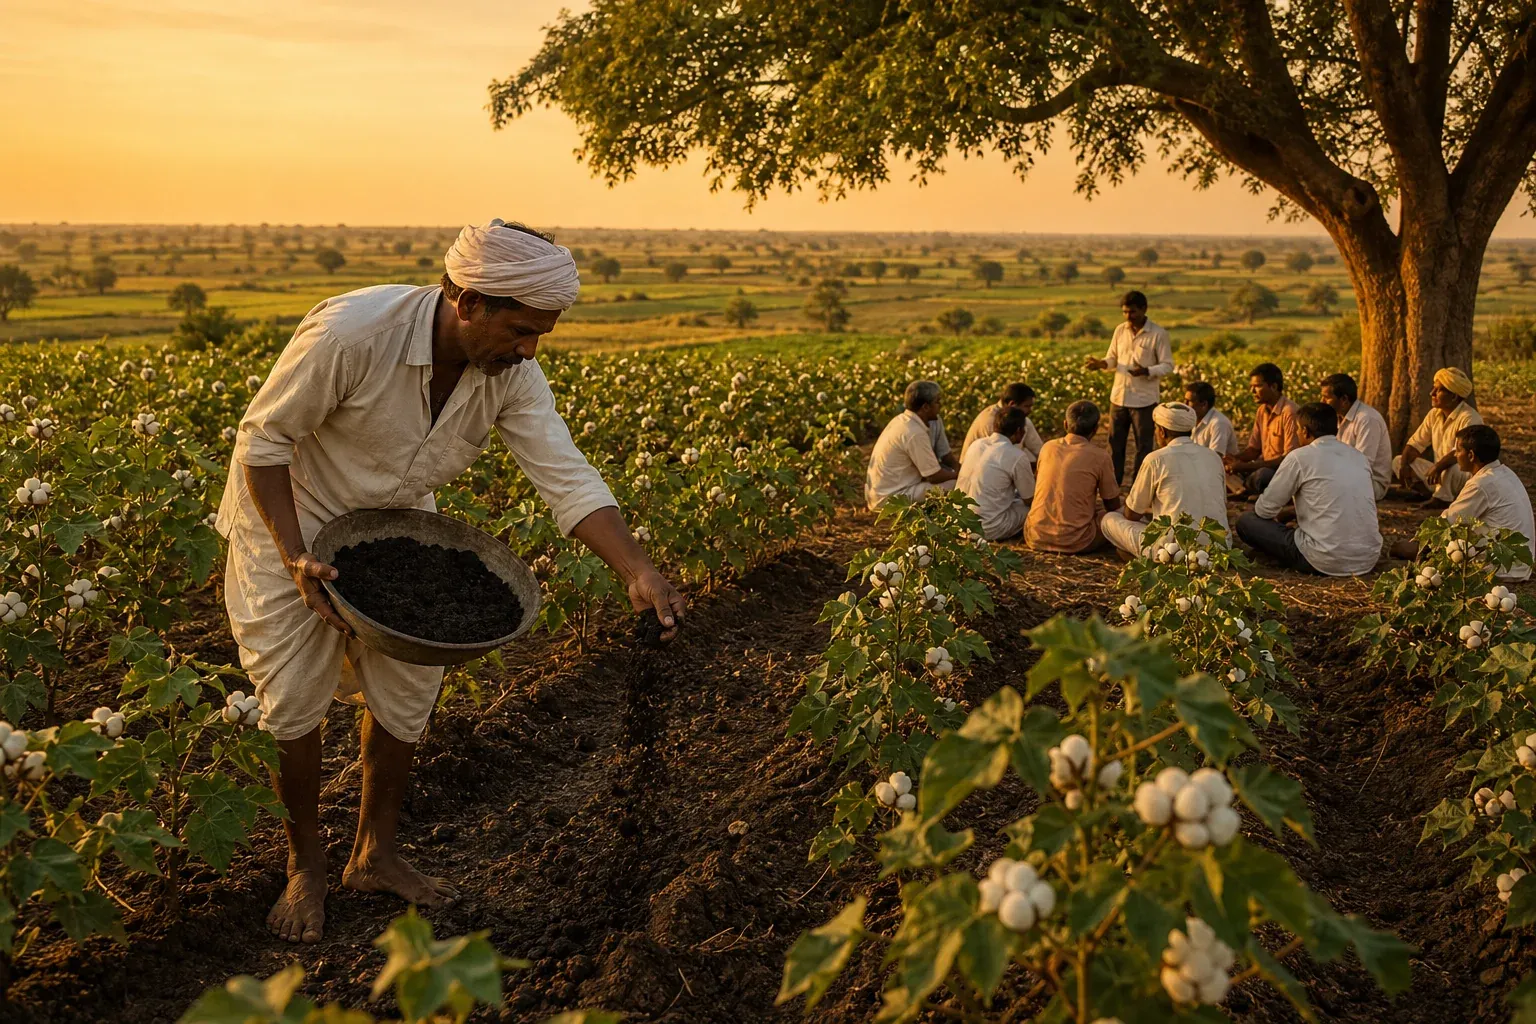
The most significant upfront cost in a carbon insetting program is farmer onboarding and capacity building. This includes training farmers in regenerative practices, establishing baseline soil carbon measurements, and building the data collection infrastructure needed for MRV. For a program covering 500 smallholder farmers across a cotton-growing region in India, initial setup costs typically range from $80,000 to $200,000, depending on geographic spread, existing farmer organisation, and the complexity of practices being introduced.
Beetle Regen's programs in India and Bangladesh are structured to reduce these costs through existing farmer networks and cooperative structures, which significantly lowers the per-farmer onboarding cost compared to building from scratch.
MRV Infrastructure
Measurement, Reporting, and Verification is the backbone of any credible insetting program. Soil testing, remote sensing integration, and digital data collection platforms are not optional, they are what separates a verified insetting claim from a marketing assertion. MRV costs for a mid-scale program (500, 2,000 farmers) typically run $30,000 to $100,000 in year one, with ongoing annual costs of $20,000–$60,000 as the system matures and data collection becomes more efficient. For more on what robust MRV looks like in practice, see our MRV and Traceability Systems for Cotton: A Complete Guide.
Biochar Production and Deployment
Biochar is one of the most durable and verifiable carbon sequestration tools available for agricultural insetting programs. In Indian cotton supply chains, biochar produced from agricultural waste (cotton stalks, rice husks) and applied to fields delivers measurable soil carbon improvements alongside yield benefits. Biochar production and deployment costs in India currently range from $60 to $120 per tonne of CO2e sequestered, depending on feedstock availability, kiln technology, and logistics. This is higher than the purchase price of a low-quality voluntary offset, but the permanence, verifiability, and supply chain attribution of biochar insetting are substantially stronger. Our detailed analysis of biochar's role in supply chain decarbonisation is available in Biochar Carbon Removal: Durability, Ratings & Who Should Care.
Traceability System Integration
Insetting programs generate value only when the carbon sequestration can be traced back to specific farms and linked to specific fibre purchases. Traceability system integration, connecting farm-level data to brand procurement systems, adds $20,000 to $50,000 in year one for a mid-scale program, with lower ongoing costs as the system stabilises. This investment, however, delivers dual value: it supports carbon claims and simultaneously enables supply chain transparency reporting required under CSRD and similar frameworks.
How Costs Scale Over Time
A critical difference between insetting and offsetting is the cost trajectory. Offset costs scale linearly with the volume of credits purchased, buy more, pay more, indefinitely. Insetting programs, by contrast, have high upfront costs that decline significantly per tonne as the program scales and matures. A program that costs $150 per tonne CO2e in year one may cost $60–$80 per tonne by year three as infrastructure is amortised and farmer practices are embedded. This makes insetting increasingly cost-competitive over a 3, 5 year horizon.
Side-by-Side Cost Comparison: Insetting vs Offsetting
The table below summarises the cost structures across both approaches for a representative mid-size textile brand with a 50,000 tonne CO2e annual footprint, targeting 20% supply chain abatement (10,000 tonnes CO2e) in year one.
| Cost Category | Carbon Offsetting | Carbon Insetting |
|---|---|---|
| Credit/Sequestration Cost (per tonne CO2e) | $8–$30 (Year 1) | $80–$150 (Year 1); $40–$80 (Year 3+) |
| Setup / Onboarding | $5,000–$15,000 (broker/registry) | $80,000–$200,000 (farmer program) |
| Annual Verification Cost | Embedded in credit price + $10,000–$30,000 internal | $20,000–$60,000 (MRV system) |
| Traceability / Reporting | Low (registry certificate only) | $20,000–$50,000 (Year 1); lower ongoing |
| Reputational Risk Premium | High and rising (greenwashing exposure) | Low (supply chain-attributed, verifiable) |
| SBTi / CSRD Compliance Value | Limited (residual emissions only) | High (counts toward Scope 3 reduction) |
| Co-Benefits (soil, farmer income, biodiversity) | Indirect / unattributed | Direct and reportable |
| 5-Year Total Cost Trajectory | Linear increase with volume | Declining per-tonne cost as program scales |
The numbers make clear that insetting carries a higher upfront cost in year one. But the 5-year picture, accounting for declining per-tonne costs, co-benefit value, and the avoided cost of reputational risk, shifts the comparison significantly in insetting's favour for brands with meaningful supply chain ownership.
Reputational Value and ESG ROI: Beyond the Price Tag
Cost-per-tonne is a useful starting point, but it misses a substantial portion of the value equation. The ESG ROI of insetting versus offsetting diverges sharply when you account for how each approach is treated by the frameworks that matter most to your investors, retail partners, and regulators.
How SBTi and CSRD Treat Each Approach
The SBTi's Corporate Net-Zero Standard is unambiguous: carbon credits (offsets) cannot be used to compensate for Scope 3 emissions reductions that a brand has committed to achieve. They can only be used to neutralise residual emissions after maximum feasible abatement. Insetting, by contrast, is recognised as a supply chain abatement activity, it counts toward your Scope 3 reduction targets, not just neutralisation. This distinction is not semantic. It is the difference between a climate strategy that satisfies SBTi validation and one that does not.
Under CSRD's double materiality framework, brands must disclose both their financial exposure to climate risk and their impact on the environment. An insetting program that improves soil health, increases farmer income, and reduces agricultural emissions in your supply chain generates disclosable positive impact across multiple ESG dimensions. An offset portfolio generates a single line item: tonnes neutralised.
Investor and Retailer Scrutiny
Institutional investors and major retail partners are increasingly sophisticated about carbon accounting. Procurement teams at large retailers now routinely ask suppliers to distinguish between emissions reductions and offset purchases in their sustainability data. Brands that can demonstrate verified supply chain abatement, with MRV data, traceability records, and farmer-level impact metrics, are better positioned in supplier scorecards and ESG ratings than those presenting an offset certificate. This translates into tangible commercial value: preferred supplier status, longer contract terms, and access to sustainability-linked financing.
Supply Chain Storytelling and Brand Differentiation
Insetting generates a narrative that offsets simply cannot. A verified program that trains 800 smallholder cotton farmers in Vidarbha to apply biochar, improves their soil organic carbon by 0.3%, and increases their household income by 18% is a story your marketing team, your ESG report, and your retail partners can use. It connects your climate investment to real people, real places, and real outcomes. That narrative has commercial value that does not appear in a cost-per-tonne calculation but is very real in brand equity terms. For more on how supply chain traceability supports this kind of storytelling, see Supply Chain Traceability for Regenerative Cotton: A Brand Guide.
The Hybrid Approach: When to Use Both
The insetting vs offsetting debate is often framed as a binary choice. In practice, most textile brands will need both, at least during the transition period before their supply chain abatement programs reach full scale.
Which Emissions Are Best Addressed by Each Approach
A practical hybrid strategy starts with a clear emissions map. Scope 3 Category 1 emissions (purchased goods and services, including raw material production) are the primary target for insetting, these are the emissions your supply chain partners generate, and they are where insetting programs operate. Scope 1 and Scope 2 emissions from your own operations should be addressed through energy efficiency and renewable energy first. Residual emissions, those that cannot be abated through operational changes or supply chain insetting, are the appropriate domain for high-quality offsets.
How to Sequence Your Investment
The sequencing logic recommended by SBTi and most credible sustainability frameworks is: reduce first, then neutralise residuals. In budget terms, this means prioritising insetting investment in your highest-emission supply chain categories (typically raw material production and wet processing), while using offsets only for emissions you genuinely cannot yet abate. A common starting allocation for brands new to insetting is 60, 70% of the climate budget toward supply chain abatement programs and 30, 40% toward high-quality offsets for residual neutralisation, with the offset share declining as the insetting program matures.
A Practical Hybrid Budget Framework
- Year 1, 2: Establish insetting program infrastructure (farmer onboarding, MRV, traceability). Use offsets for residual neutralisation while the insetting program builds toward verification. Budget split: ~40% insetting setup, ~60% offsets.
- Year 3, 4: Insetting program reaches verification milestone. First verified insetting credits attributed to supply chain. Offset reliance begins to decline. Budget split: ~60% insetting, ~40% offsets.
- Year 5+: Insetting program at scale. Per-tonne costs declining. Offsets reserved for genuinely residual emissions only. Budget split: ~75, 80% insetting, ~20, 25% offsets.
This trajectory aligns with SBTi's expectations for net zero pathways and positions the brand to make credible, auditable claims at each stage of the journey. For a comprehensive look at how regenerative agriculture fits into this kind of long-term strategy, see our Sustainable Farming: A Complete Guide to Regenerative Agriculture.
How to Decide: A Decision Framework for Brands
Not every brand is at the same stage of supply chain ownership or sustainability maturity. The right balance between insetting and offsetting depends on several factors that are specific to your organisation.
Key Decision Criteria
- Supply chain ownership: Do you have direct relationships with farmers or raw material suppliers? Brands with traceable, long-term supplier relationships are better positioned to implement insetting programs. Brands with fragmented, spot-market sourcing may need to build those relationships first.
- Timeline to net zero commitment: If your public commitment is 2030 or earlier, you need insetting programs running now, the 2, 3 year ramp-up to verified credits means there is no time to delay. If your horizon is 2040+, you have more flexibility to phase the transition.
- Budget size and internal capacity: Insetting programs require active management. Brands without dedicated sustainability staff may benefit from a Sustainability as a Service model that provides external program management, MRV oversight, and reporting support.
- Regulatory exposure: Brands selling into EU markets face CSRD and the EU Green Claims Directive. Brands listed on Indian stock exchanges face BRSR requirements. The regulatory direction in both markets strongly favours supply chain abatement over offset-based claims.
- Fibre sourcing geography: Brands sourcing cotton from India or Bangladesh have access to established insetting program infrastructure through partners like Beetle Regen, which significantly reduces setup costs and timelines compared to building programs in less-developed markets.
Questions to Ask Before Committing Budget
- What percentage of our Scope 3 emissions come from raw material production, and do we have supplier relationships that could support an insetting program?
- Have we mapped our supply chain to the farm level, or are we still working with aggregated supplier data?
- What does our SBTi pathway require in terms of Scope 3 reduction by 2030, and can offsets alone satisfy that requirement?
- What is the reputational risk profile of our current offset portfolio, are the credits we are buying likely to withstand NGO or investor scrutiny?
- Do we have the internal capacity to manage an insetting program, or do we need a managed service partner?
Beetle Regen's insetting programs in India and Bangladesh are designed to be accessible to brands at different stages of this journey. Whether you are starting with a pilot program covering a single cotton-growing region or scaling an established insetting initiative, the program structure is built around your supply chain's existing geography and supplier relationships. The Carbon Insetting Solutions framework provides a practical starting point for understanding what a program in your supply chain could look like.
For brands that want to understand the data infrastructure required to support insetting claims, our guide on How to Integrate Regenerative Agriculture Data Across Supply Chains covers the technical requirements in detail.
Frequently Asked Questions
Can insetting credits replace offsets for SBTi compliance?
Insetting credits count toward Scope 3 emission reductions under SBTi's Corporate Net-Zero Standard, which is a more valuable designation than offsets used for neutralisation. However, insetting does not replace the need for operational emission reductions in Scope 1 and Scope 2. The correct framing is that insetting addresses supply chain abatement, while offsets address residual neutralisation, both have a role, but insetting carries more weight in SBTi validation.
What is the minimum supply chain size for insetting to be cost-effective?
As a general benchmark, insetting programs become cost-competitive with high-quality offsets at around 500, 1,000 tonnes CO2e of annual sequestration target, which typically corresponds to a farmer program covering 300, 600 smallholders. Below this threshold, the fixed costs of MRV and program management make the per-tonne cost prohibitive. Brands below this threshold may benefit from joining a shared insetting program or pooled credit structure, which Beetle Regen facilitates for smaller brands entering the market.
How long does it take to see ROI from a carbon insetting program?
The first verified insetting credits from a new program typically take 18, 30 months from program launch, depending on the MRV protocol used and the verification body's timeline. However, co-benefits, improved supplier relationships, supply chain data, and ESG reporting material, begin accruing from the first season of farmer engagement. Brands should plan for a 2, 3 year investment horizon before the program reaches full financial efficiency.
Are insetting costs eligible for green finance or sustainability-linked loans?
In many cases, yes. Sustainability-linked loans (SLLs) and green bonds can be structured to fund supply chain decarbonisation programs, including insetting infrastructure. Several development finance institutions active in India and Bangladesh, including the IFC and FMO, have specific facilities for supply chain sustainability investments. Brands should work with their treasury and sustainability teams to explore whether their insetting program qualifies for preferential financing. This is an area where Beetle Regen can connect brands with relevant financing partners.
How does biochar insetting compare in cost to soil carbon insetting through regenerative practices?
Biochar insetting typically has a higher upfront cost per tonne CO2e ($60–$120) compared to soil carbon sequestration through regenerative practices like cover cropping or reduced tillage ($20–$60 per tonne), but it offers significantly higher permanence (hundreds to thousands of years versus decades for soil organic carbon) and more straightforward MRV. For brands that need durable, auditable carbon claims, biochar's higher cost is often justified. For brands prioritising co-benefits like soil health and yield improvement, a combination of regenerative practice adoption and biochar application delivers the strongest overall value. See our detailed breakdown in Carbon Sequestration in Agriculture: A Complete Framework.
Make Your Climate Budget Work Harder
The carbon insetting vs offsetting cost comparison ultimately comes down to a question of what kind of climate investment your brand wants to make. Offsets are a financial instrument. Insetting is a supply chain transformation. Both have costs, but only one builds the verified, traceable, supply chain-attributed impact that regulators, investors, and retail partners are increasingly demanding.
For textile brands sourcing from India or Bangladesh, the infrastructure to run a credible, cost-efficient insetting program already exists. The question is not whether insetting is feasible, it is whether your brand is ready to move from purchasing climate outcomes to creating them.
If you are ready to map your supply chain's insetting potential, understand what a program would cost at your scale, and build a hybrid strategy that satisfies your SBTi pathway, connect with the Beetle Regen team for a structured conversation about where your climate budget can go furthest. Bring your emissions data, your sourcing geography, and your net zero timeline, and we will help you build the numbers that make the case internally.