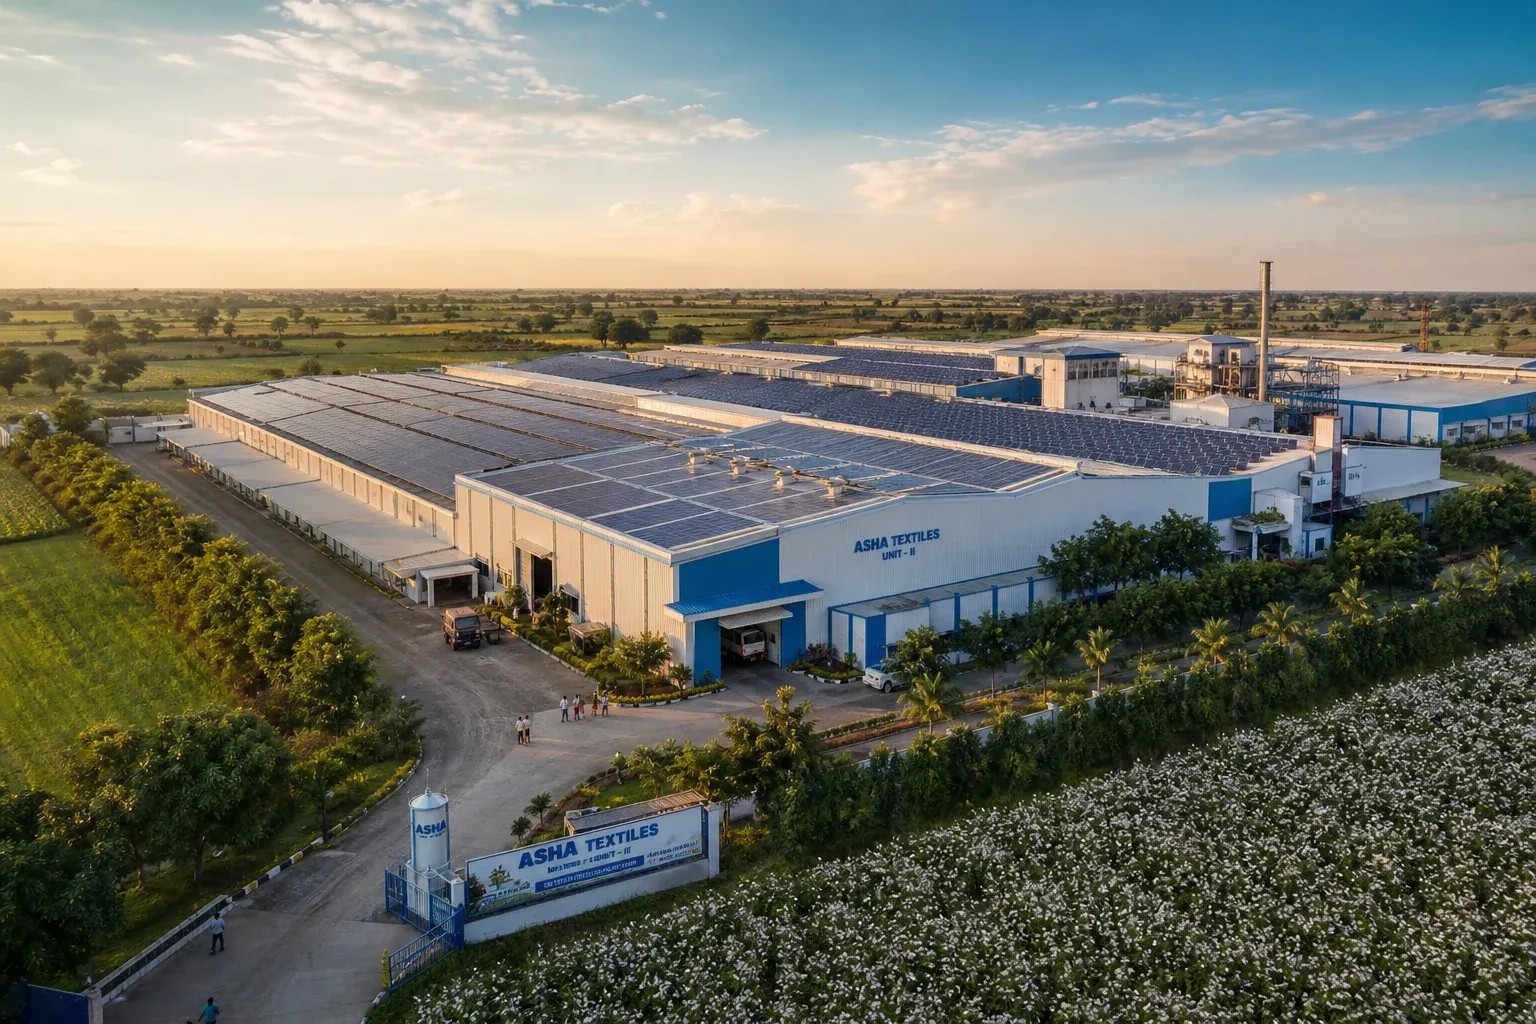
Net Zero Roadmap for Textile Manufacturers in 2026
Somewhere between a brand's net zero pledge and the factory floor, the roadmap breaks down. A garment maker in Tirupur or a yarn producer in Coimbatore receives a supplier questionnaire from a European buyer asking for Scope 3 emissions data, a decarbonisation plan, and evidence of progress against science-based targets. The sustainability team — if there is one — opens a blank spreadsheet. The procurement team forwards the email to operations. Operations forwards it back. Nothing moves.
This is not a knowledge problem. Most textile manufacturers understand that climate commitments matter. The gap is structural: there is no step-by-step framework built specifically for manufacturers — as distinct from the brands they supply, that connects emissions baselining to sourcing decisions to traceability systems to regulatory compliance. This guide fills that gap.
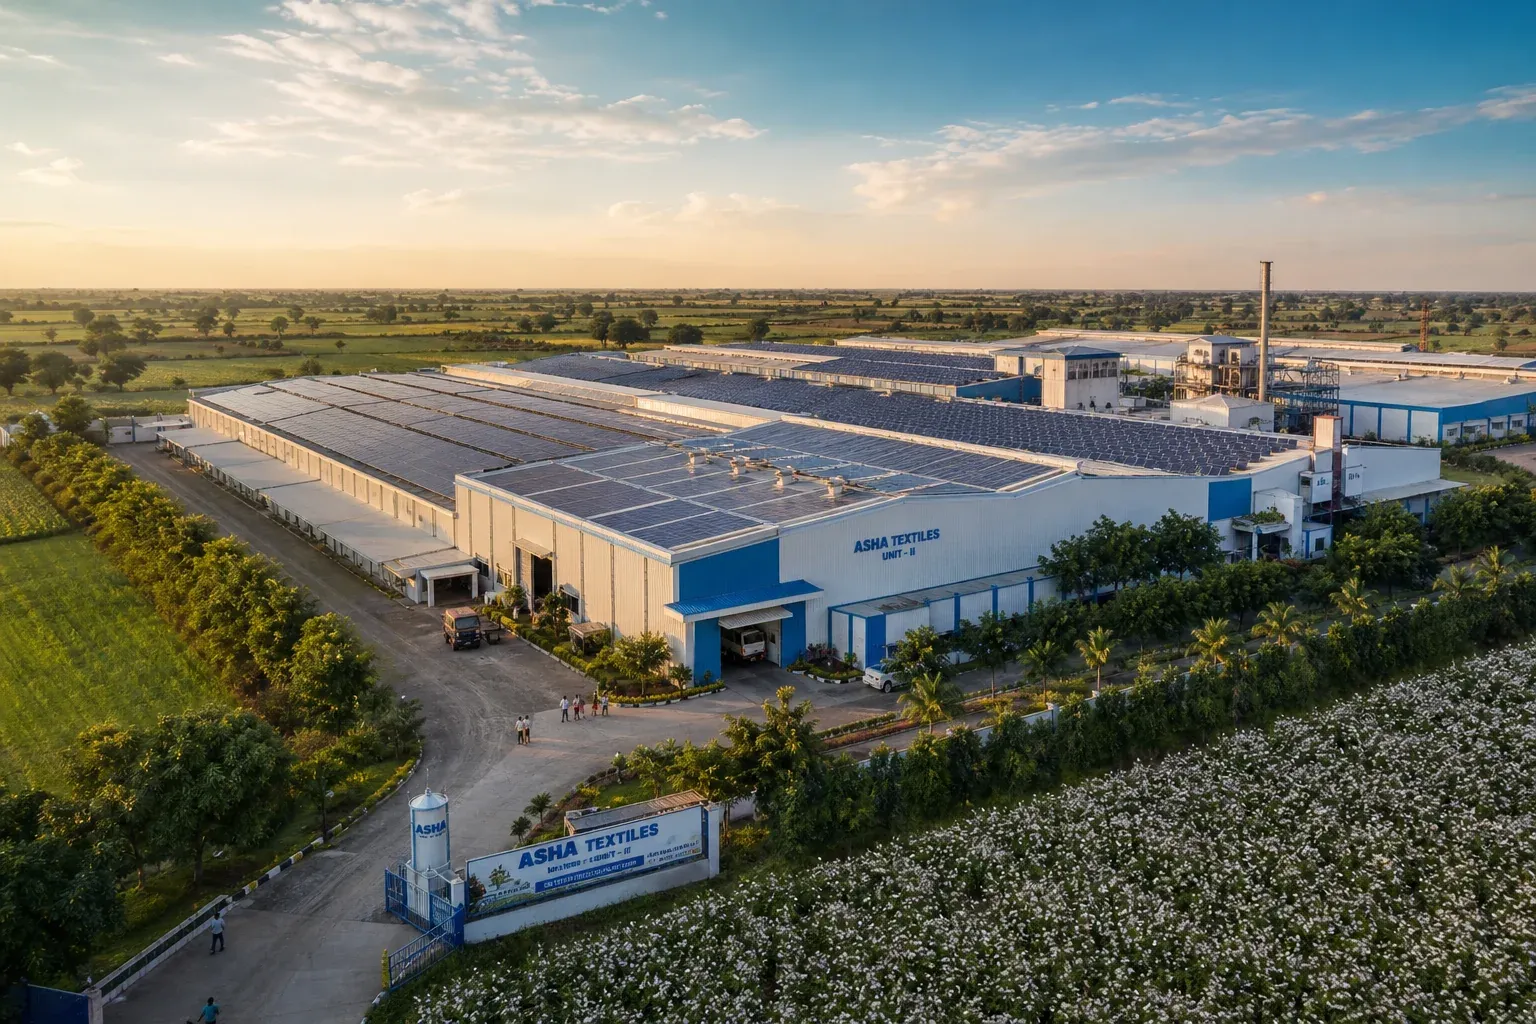
Why Textile Manufacturers Need a Structured Net Zero Roadmap Now
The regulatory environment shifted decisively in 2026. The EU Corporate Sustainability Reporting Directive (CSRD) now requires large European companies to disclose Scope 3 value chain emissions, which means their suppliers, including Indian and Bangladeshi textile manufacturers, must provide verified emissions data or risk losing contracts. India's Business Responsibility and Sustainability Reporting (BRSR) Core framework has extended mandatory ESG disclosures to the top 1,000 listed companies, with supply chain reporting requirements cascading further downstream.
Buyer pressure is moving faster than regulation. Brands like H&M, Primark, C&A, and Marks & Spencer have published supplier sustainability requirements that include carbon reduction milestones, traceability documentation, and evidence of responsible sourcing. Manufacturers who cannot provide this data are being deprioritized in sourcing decisions, not because buyers want to penalize them, but because the brands themselves face audit exposure if their supply chain data is incomplete.
A net zero roadmap for a textile manufacturer is not the same as a brand's roadmap. Brands focus heavily on Scope 3 Category 1 (purchased goods) and consumer-facing claims. Manufacturers must address Scope 1 emissions from their own production processes, Scope 2 from energy procurement, and Scope 3 from both upstream fiber inputs and downstream product use. The structure, the milestones, and the evidence requirements are different, and that distinction matters when building something credible enough to satisfy an auditor.
The difference between a net zero pledge and a net zero roadmap is evidence. A pledge is a statement of intent. A roadmap is a documented, time-bound plan with baselines, milestones, responsible owners, and verified progress data.
1. Establish Your Emissions Baseline Across Scope 1, 2, and 3
Every credible roadmap starts with a number you can defend. Before setting targets or selecting interventions, a textile manufacturer needs a complete GHG inventory that covers all three scopes.
Scope 1: Direct Emissions From Your Operations
Scope 1 emissions come from sources your facility owns or controls directly. For textile manufacturers, this typically includes combustion in coal or gas-fired boilers used for steam generation, diesel generators, and chemical processes in dyeing and finishing. These are the emissions most manufacturers already track to some degree, but the methodology matters. Using the GHG Protocol Corporate Standard and applying the correct emission factors for your fuel types and geography is essential for CSRD-aligned reporting.
Scope 2: Purchased Energy
Scope 2 emissions come from the electricity and heat you buy. India's grid emission factor varies significantly by state, a mill in Tamil Nadu drawing from the Southern Regional Grid has a different baseline than one in Maharashtra. The market-based method (using renewable energy certificates or power purchase agreements) versus the location-based method produces different numbers, and CSRD requires both to be disclosed. Switching to renewable energy procurement is one of the fastest levers for Scope 2 reduction, but it must be documented correctly to count.
Scope 3: Your Largest and Most Complex Category
For most textile manufacturers, Scope 3 Category 1 (purchased goods and services), primarily raw fiber inputs like cotton, polyester, and viscose, accounts for 60 to 80 percent of total emissions. This is where the roadmap gets difficult, and where most manufacturers stall. Calculating upstream emissions from cotton requires farm-level data: fertilizer application rates, irrigation energy, land use change, and soil carbon status. Without a traceability system connecting your mill to specific farms, you are working with industry averages that will not satisfy a CSRD auditor or a buyer's ESG team.
Common baselining mistakes include using outdated emission factors, excluding Scope 3 categories on the grounds of immateriality without proper screening, and conflating carbon intensity (emissions per kilogram of output) with absolute emissions. Your baseline year matters too, most SBTi-aligned targets use a 2019 or 2020 base year, but manufacturers starting now should document their rationale clearly.
For a deeper look at how to carbon footprint your textile supply chain systematically, see How to Carbon Footprint Your Textile Supply Chain.
2. Set Science-Based Targets That Reflect Your Value Chain
Once you have a baseline, the next step is setting targets that are credible, meaning they align with the science of limiting global warming to 1.5°C, not just with what feels achievable internally.
The Science Based Targets initiative (SBTi) provides the most widely recognized framework. For textile manufacturers with significant agricultural inputs, the FLAG (Forest, Land and Agriculture) guidance is directly relevant, it sets separate reduction pathways for land-related emissions, which include cotton cultivation. Near-term targets typically cover a 5-10 year window (e.g., 42% absolute reduction by 2030 from a 2019 base), while long-term net zero targets extend to 2050.
Indian manufacturers supplying EU brands need to align their target-setting with CSRD's double materiality assessment requirements. This means identifying not just how climate change affects your business (financial materiality) but how your business affects the climate (impact materiality). BRSR Core, which applies to listed Indian companies, requires disclosure of Scope 1, 2, and 3 emissions and transition plans, making SBTi alignment a practical compliance tool, not just a voluntary signal.
The most common trap at this stage is setting targets without a delivery mechanism. A target of "net zero by 2045" means nothing without a documented plan for how you will reduce Scope 3 Category 1 emissions, which requires engaging your fiber suppliers, not just your energy provider.
For context on how EU CSRD Scope 3 reporting requirements affect textile supply chains specifically, the EU CSRD Scope 3 Reporting guide provides a detailed breakdown of disclosure obligations.
3. Prioritize Carbon Insetting Over Offsetting in Your Supply Chain
This is where most manufacturer roadmaps diverge from brand roadmaps, and where the most credible emissions reductions happen.
Carbon offsetting means purchasing credits from projects outside your value chain to compensate for emissions you have not reduced. It has a role in residual emissions management, but it does not reduce your actual Scope 3 footprint, and CSRD explicitly requires manufacturers to distinguish between genuine reductions and offset-based claims.
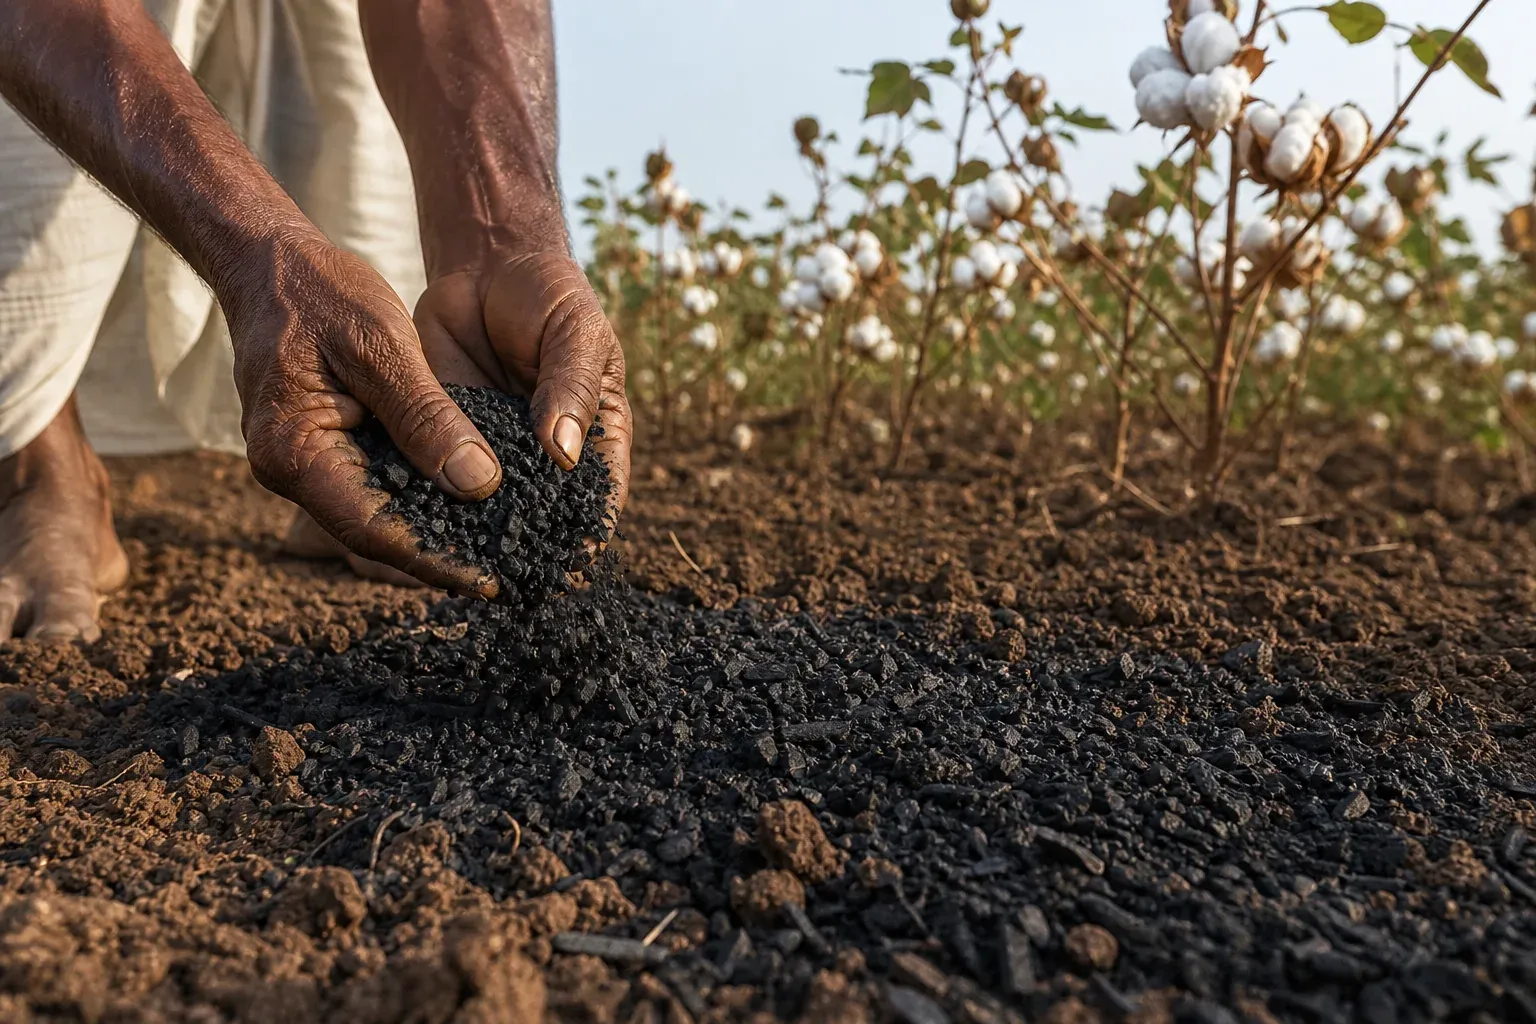
Carbon insetting means investing in emissions reductions or carbon sequestration within your own supply chain. For a cotton-sourcing manufacturer, this means funding regenerative agriculture practices and biochar production on the farms that grow your fiber. The carbon sequestered in those soils counts against your Scope 3 Category 1 emissions, and the evidence is traceable to specific farms in your supply chain.
Biochar-Based Carbon Insetting: How It Works
Biochar is produced by pyrolyzing agricultural residues, crop stalks, husks, and other biomass that would otherwise be burned or left to decompose. When applied to cotton farmland, biochar improves soil water retention, increases microbial activity, and sequesters carbon in a stable form that persists for hundreds of years. Programs operating in Maharashtra and Madhya Pradesh are generating verified carbon sequestration at scale, with MRV (Measurement, Reporting, Verification) documentation that meets Verra and Gold Standard protocols.
The cost per tonne of CO₂ sequestered through biochar insetting in Indian cotton supply chains is competitive with voluntary carbon market offsets, and unlike offsets, the sequestration happens in your supply chain, generating traceability data as a co-benefit. For manufacturers under CSRD pressure, that distinction is significant. To understand the full mechanics, Carbon Insetting Solutions: Decarbonize Your Textile Supply Chain covers the program structure in detail.
Regenerative Cotton as a Dual Lever
Sourcing regenerative cotton reduces Scope 3 Category 1 emissions through lower synthetic fertilizer use, improved soil carbon sequestration, and reduced irrigation energy. It also generates the farm-level data, soil organic carbon measurements, input records, yield data, that your traceability system needs to evidence Scope 3 reductions to auditors and buyers. This dual function makes regenerative sourcing one of the highest-leverage interventions in a manufacturer's roadmap.
For a detailed comparison of insetting versus offsetting economics, see Carbon Insetting vs Carbon Credits: What Brands Should Buy.
4. Integrate Regenerative Cotton Sourcing Into Your Fiber Procurement
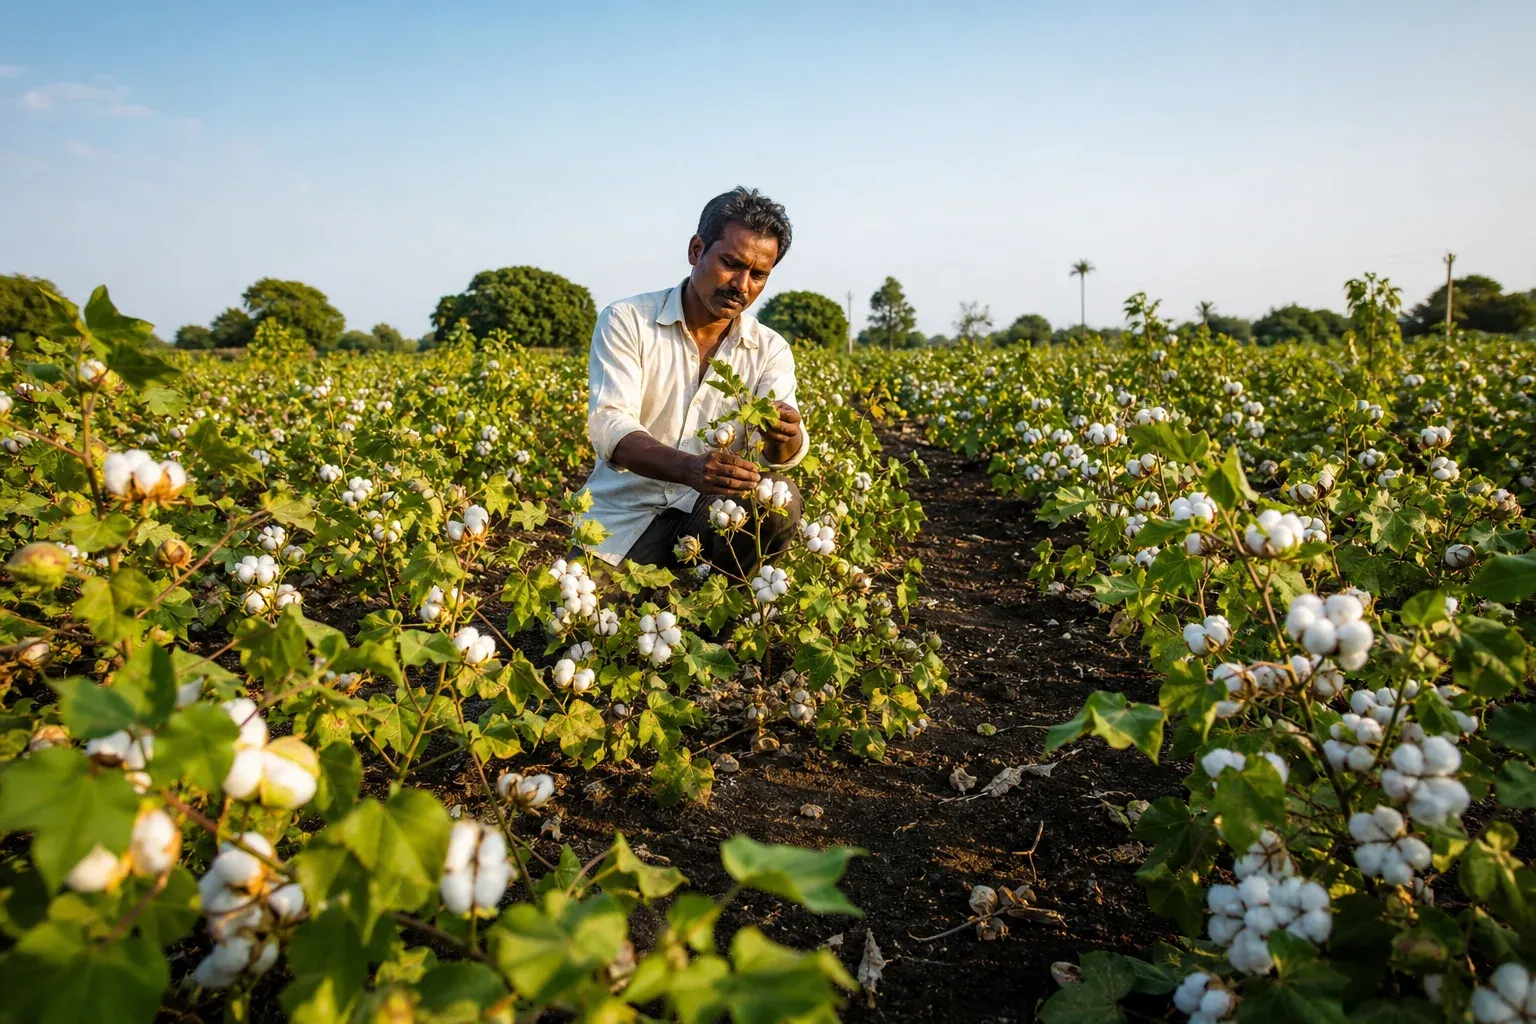
Transitioning fiber procurement to verified regenerative sources is one of the most impactful steps in a manufacturer's net zero roadmap, and one of the most practically complex. Here is how to approach it systematically.
What Regenerative Cotton Certification Looks Like in India
Unlike organic certification, which focuses primarily on input restrictions, regenerative cotton certification for Indian smallholder farms is outcomes-based. It measures soil organic carbon improvement, biodiversity indicators, water use efficiency, and farmer livelihood metrics. Programs operating in Gujarat, Maharashtra, Telangana, and Madhya Pradesh train farmers in practices including cover cropping, reduced tillage, compost application, and biochar use, then verify outcomes through soil testing and satellite monitoring.
The certification process for smallholder farms typically runs 12 to 24 months from program enrollment to first verified harvest. This timeline matters for procurement planning: manufacturers transitioning away from conventional or Better Cotton Initiative (BCI) supply need to build a 2-year pipeline, not a 6-month one.
Linking Regenerative Sourcing to Scope 3 Evidence
The connection between regenerative sourcing and Scope 3 reduction claims requires documented evidence, not just supplier declarations. Soil organic carbon measurements taken at baseline and annually thereafter, combined with input records showing reduced synthetic fertilizer use, provide the quantitative basis for calculating emission reductions per kilogram of cotton. This data must flow from the farm through the gin and spinning mill to your facility, which is why traceability infrastructure is inseparable from sourcing strategy.
For a full overview of the India and Bangladesh sourcing landscape, including key growing regions and program structures, see Regenerative Cotton Sourcing India & Bangladesh: Brand Guide.
5. Build a Traceability System That Evidences Progress
A net zero roadmap without a traceability system is a document. A roadmap with traceability is a compliance asset. The distinction matters because CSRD, BRSR, and buyer ESG audits all require evidence, not assertions.
What Traceability Infrastructure Looks Like for Manufacturers
Farm-to-mill traceability means capturing GPS coordinates of source farms, farming practice records (inputs applied, tillage methods, cover crop use), soil test results, harvest volumes, and chain-of-custody documentation through ginning and spinning. For a fabric mill or garment manufacturer, this data does not need to be generated internally, it needs to flow from your fiber suppliers through a shared digital platform.
Digital MRV systems, Measurement, Reporting, and Verification platforms, automate the collection and verification of carbon sequestration data from farms. When integrated with your procurement records, they allow you to calculate the carbon intensity of specific cotton lots, not just your supply chain average. This granularity is what separates a credible Scope 3 reduction claim from a generic sustainability statement.
Connecting Traceability to ESG Reporting
The data captured in a traceability system needs to connect to your ESG reporting tools, whether that is the Higg Index, GRI Standards, CSRD-aligned ESRS disclosures, or BRSR Core. This integration is not automatic. It requires mapping your traceability data fields to the disclosure requirements of each framework, and building reporting workflows that can be audited. For a practical guide to this integration, MRV and Traceability Systems for Cotton: A Complete Guide covers the technical architecture in detail.
Greenwashing risk is highest at the point where traceability data meets public claims. Auditors and buyers are increasingly checking whether the carbon sequestration figures in sustainability reports are supported by farm-level MRV data, and whether the regenerative sourcing claims are backed by chain-of-custody documentation. Manufacturers who build robust traceability infrastructure are protected; those who rely on supplier declarations are exposed.
6. Operationalize With Milestones, Governance, and Reporting Cadence
A roadmap that exists only as a strategy document will not survive contact with procurement cycles, production pressures, and annual reporting deadlines. Operationalizing it requires three things: a milestone framework, clear governance, and a reporting cadence that aligns with external disclosure requirements.
A Practical Milestone Framework
The following timeline works for most mid-sized textile manufacturers starting their net zero journey in 2026:
- Months 1, 12: Complete GHG baseline (Scope 1, 2, and 3). Identify top 3 emission hotspots. Enroll in SBTi target-setting process. Audit current fiber suppliers for regenerative sourcing readiness. Select a traceability platform.
- Months 13, 36: Submit SBTi near-term targets. Transition 20, 30% of cotton procurement to verified regenerative sources. Launch biochar insetting program with at least one supplier cluster. Implement farm-to-mill traceability for regenerative supply. Publish first CSRD/BRSR-aligned progress disclosure.
- Months 37, 60: Scale regenerative sourcing to 50%+ of cotton volume. Achieve verified Scope 3 Category 1 reduction of 15, 25% against baseline. Integrate traceability data with ESG reporting tools. Prepare for third-party verification of net zero progress claims.
Governance: Who Owns the Roadmap
The most common reason roadmaps stall is unclear ownership. Sustainability strategy, procurement decisions, and production operations are typically managed by different teams with different incentives. A net zero roadmap requires a cross-functional steering group with representation from sustainability, procurement, and operations, and a named executive sponsor who can resolve conflicts between cost pressures and climate commitments.
Common Pitfalls to Avoid
Manufacturers who have attempted net zero roadmaps without structured support consistently encounter the same obstacles: siloed teams that do not share data, suppliers who lack the capacity to provide farm-level emissions information, and reporting frameworks that change faster than internal systems can adapt. The solution is not to wait for perfect conditions, it is to build incrementally, document your methodology, and engage suppliers as partners rather than data sources.
7. Accelerate Delivery With Sustainability as a Service (SaaS) Partnerships
Building a net zero roadmap internally requires capabilities that most textile manufacturers do not have in-house: carbon accounting expertise, regenerative agriculture program management, MRV system implementation, traceability platform integration, and regulatory compliance tracking across CSRD, BRSR, and buyer-specific ESG frameworks. The gap between what is required and what most sustainability teams can deliver is significant.
This is the problem that Sustainability as a Service (SaaS) partnerships are designed to solve. Rather than hiring a full sustainability team and building proprietary systems, manufacturers can access an integrated service that covers carbon footprinting, regenerative sourcing program management, biochar insetting, traceability implementation, and compliance reporting, as a managed service with defined deliverables and timelines.
What an Integrated SaaS Partner Delivers
Beetle Regen's model combines four capabilities that are typically sourced separately: regenerative cotton supply (verified, traceable, from smallholder programs in India and Bangladesh), biochar-based carbon insetting (with MRV documentation meeting Verra and Gold Standard protocols), supply chain traceability infrastructure (farm-to-mill data flows integrated with ESG reporting tools), and compliance strategy (CSRD, BRSR, and buyer ESG alignment). For a yarn producer or fabric mill that needs to respond to a buyer's sustainability questionnaire within 90 days, this integrated model reduces time-to-compliance significantly compared to building each capability independently.
The Climate Action Textile Forum, facilitated by Beetle Regen, provides manufacturers with a collaborative platform to engage with peers, brands, and policymakers on shared sustainability challenges, reducing the isolation that many sustainability teams feel when navigating complex regulatory environments alone.
Selecting the Right Partner
When evaluating a SaaS sustainability partner, ask these questions: Can they provide verified farm-level data, or do they rely on industry averages? Do their carbon sequestration claims meet recognized MRV protocols? Can they demonstrate chain-of-custody documentation from farm to mill? Do they have experience with CSRD and BRSR compliance specifically, or only with voluntary sustainability frameworks? The answers will quickly distinguish partners who can deliver evidence from those who can only deliver reports.
For manufacturers earlier in their sustainability journey, Sustainability as a Service Model: A Beginner's Guide provides a clear overview of how the model works and what to expect from a partnership engagement.
Understanding how regenerative agriculture practices align with broader climate policy frameworks is also valuable context for manufacturers engaging with government and regulatory stakeholders, How Regenerative Agriculture Aligns with Climate Policy covers this in depth.
Frequently Asked Questions
How long does it take to build a credible net zero roadmap for a textile manufacturer?
A credible baseline and initial target-setting process typically takes 3 to 6 months. A full roadmap with milestones, governance structures, and initial supplier engagement takes 6 to 12 months. The first verified progress disclosure, showing actual Scope 3 reductions against baseline, is typically achievable within 24 to 36 months of starting, provided traceability and insetting programs are launched in parallel with target-setting.
What is the difference between carbon insetting and carbon offsetting for manufacturers?
Carbon offsetting involves purchasing credits from projects outside your supply chain to compensate for emissions you have not reduced. Carbon insetting involves funding emissions reductions or carbon sequestration within your own supply chain, for example, biochar application on the cotton farms that supply your mill. Insetting generates Scope 3 reduction evidence; offsetting does not. CSRD requires manufacturers to distinguish between the two in their disclosures.
Do Indian textile manufacturers need to comply with EU CSRD?
Indian manufacturers are not directly subject to CSRD, but their European brand customers are. CSRD requires large EU companies to disclose Scope 3 value chain emissions, which means they must collect verified emissions data from their suppliers, including Indian manufacturers. Manufacturers who cannot provide this data risk losing contracts with EU-based brands. BRSR Core applies directly to listed Indian companies and has its own supply chain reporting requirements.
How does regenerative cotton reduce Scope 3 emissions for a manufacturer?
Regenerative cotton farming reduces synthetic fertilizer use (a major source of nitrous oxide emissions), improves soil organic carbon (sequestering CO₂ from the atmosphere), and reduces irrigation energy consumption. When these reductions are measured and verified through MRV protocols, they can be applied against a manufacturer's Scope 3 Category 1 emissions baseline, reducing the reported carbon intensity of purchased cotton inputs.
What does Sustainability as a Service include for a fabric mill or yarn producer?
A comprehensive SaaS engagement for a textile manufacturer typically includes: GHG baseline assessment (Scope 1, 2, and 3), science-based target development, regenerative fiber sourcing program access, biochar carbon insetting with MRV documentation, supply chain traceability implementation, and compliance reporting aligned with CSRD, BRSR, and buyer ESG frameworks. The scope varies by manufacturer size and starting point, the right entry point is a structured assessment of your current emissions profile and compliance gaps.
Build Your Net Zero Roadmap With Partners Who Work in Your Supply Chain
The manufacturers who will meet their 2030 climate targets are not the ones with the most ambitious pledges, they are the ones who started building the evidence infrastructure early. A credible net zero roadmap for a textile manufacturer requires a baseline you can defend, targets aligned with science, insetting programs that reduce Scope 3 at source, regenerative sourcing that generates traceability data as a co-benefit, and governance structures that keep the roadmap alive through procurement cycles and reporting deadlines.
Beetle Regen works directly with yarn producers, fabric mills, and garment manufacturers to build exactly this, combining regenerative cotton supply, biochar-based carbon insetting, MRV-backed traceability, and CSRD/BRSR compliance strategy into a single integrated program. If your team is facing a buyer sustainability questionnaire, a CSRD disclosure deadline, or simply a blank spreadsheet where your net zero plan should be, the right next step is a structured conversation about where you are and what a realistic roadmap looks like for your specific value chain.
Reach out to Beetle Regen's team to start with a supply chain emissions assessment and identify the highest-impact interventions for your facility and sourcing profile.